

MyCard - Contactless Payment

- 120.00 Reviews
- 4.0
- Downloads
- 10,000+
Our take on MyCard - Contactless Payment from Appgk
MyCard - Contactless Payment is the kind of finance app that makes an immediate promise: turn a compatible phone into something you can use like a contactless bank card. I spent time looking at it from the point of view of someone who wants fewer things in a wallet, not someone searching for a novelty experiment. That distinction matters, because the first impression is appealing, while the long-term usefulness depends on whether the app fits naturally into your existing payment routine.
Developed by Road Dogs, this paid app costs $17.99 and is aimed at people comfortable with using their phone at a payment terminal. It is listed for Everyone, works from Android 5.0 onward, and its current version is 1.21. The app has reached over ten thousand installs, with a 4.0 average from around three hundred ratings and roughly one hundred twenty written reviews. Those figures suggest a small but established audience rather than a mainstream payment service that everybody already carries.
What using MyCard feels like at first
The first-week appeal is easy to understand. A physical card is one more object to remember, while a phone is usually already in your hand when you leave home. If your daily routine includes quick purchases and you prefer not to take out a wallet, contactless payment can feel wonderfully direct. The attraction is not a long list of financial tools; it is the possibility of making one ordinary action—paying—less dependent on a separate piece of plastic.
That simplicity is also the main reason to consider this particular app. MyCard is not presented as a budgeting platform, investment service, or full banking replacement. I would approach it as a focused payment utility. That narrow purpose can be a strength when you only want a mobile card experience, but it also means the app has to earn its place through dependable everyday use rather than through a broad collection of extras.
Best Parts of MyCard - Contactless Payment
Things to Keep in Mind About MyCard - Contactless Payment
Before paying for it, I would think about the exact phone and payment environment involved. The minimum operating system is Android 5.0, but an eligible Android version alone does not guarantee that every phone, bank card, or payment terminal will behave identically. Contactless payments rely on the phone’s hardware and the way the payment setup is supported. In practical terms, I would not buy it solely because an older phone meets the operating-system requirement. I would first make sure the device is genuinely suitable for NFC payments and that the intended card and payment locations are compatible with the way I shop.
That is the first important trade-off: the app can reduce dependence on a physical card, but it cannot remove the conditions that make contactless payment possible. A phone with weak NFC behavior, a damaged case that interferes with tapping, or a payment environment that expects a different method can turn a promising setup into a frustrating one. The store summary makes the purpose clear, but the real decision is whether your hardware and daily checkout habits support that purpose.
News and Features Related to MyCard - Contactless Payment

News
YouTube Turns a Quick Video Check Into an Hour of Watching

News
BeautyPlus Makes Portrait Retouching Feel Like Your Own

News
TikTok’s Effortless Feed Makes Every Swipe Count—and Every Mistake Harder to Undo
A realistic everyday test
Imagine leaving home for a short errand with your phone but no wallet. You stop for coffee, hold the phone near the terminal, and complete the purchase without searching through pockets or a bag. That is where MyCard makes the strongest case for itself. The benefit is especially noticeable for quick, repeated purchases where taking out a separate card feels unnecessary. Once the action becomes familiar, the phone can serve as a convenient payment object rather than merely a screen for checking finances.
For this scenario to become dependable, I would build a backup habit during the first week. I would carry a physical card until I had tested the app at several ordinary terminals, then keep one alternative available for situations involving a low battery, a phone restart, or an unfamiliar checkout. That is not a criticism unique to Road Dogs; it is simply the sensible discipline of relying on a phone for something as important as payment. The more central the app becomes, the less wise it is to treat the phone as infallible.
Don't want to read the full review?
I also found that contactless payment works best when I prepare before reaching the cashier. I keep the phone accessible, avoid burying it under other objects, and make sure I know which part of the device should approach the terminal. A few seconds saved at checkout can disappear if I am still unlocking, repositioning, or searching for the correct screen while a queue forms behind me. MyCard’s value comes from a smooth routine, not from merely having the app installed.
Who benefits most from the focused design
I would recommend considering MyCard if you already think of your phone as your main everyday tool and want to consolidate payment around it. It may suit someone who dislikes carrying a wallet, someone who frequently makes small in-person purchases, or someone who wants a dedicated contactless option without adopting a larger financial-management app. The focused nature is useful for a reader who does not need spending charts, account aggregation, or a crowded home screen.
Screenshots
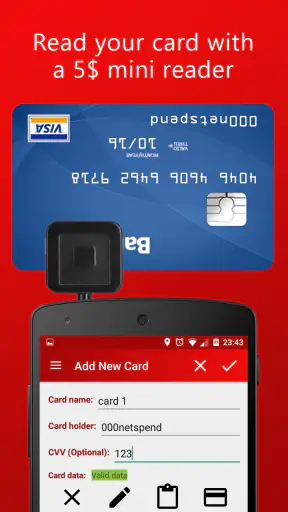
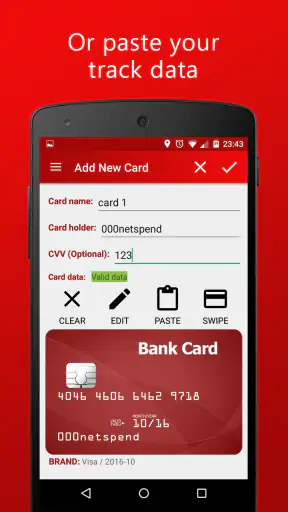
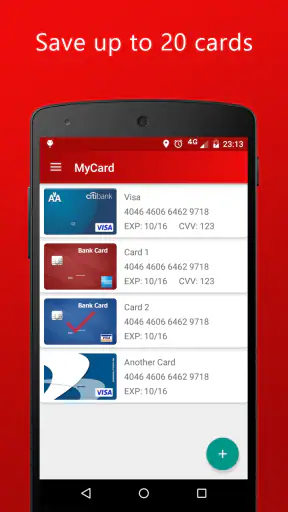
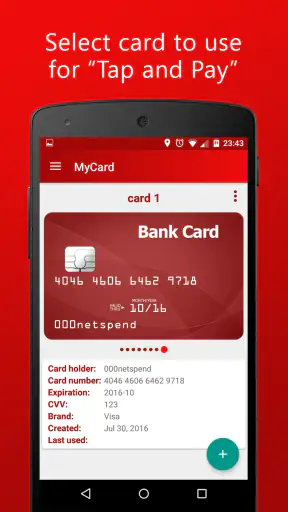
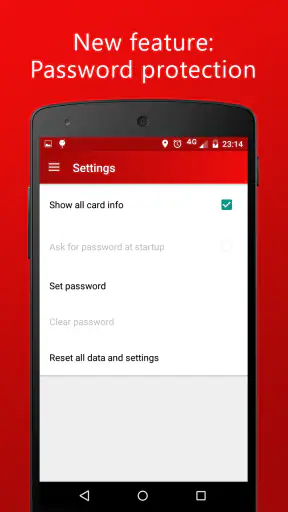
It is less convincing for someone who wants a complete banking companion. If your priority is seeing balances, categorizing spending, managing several accounts, or receiving a wider range of financial services, a conventional banking app or a broader mobile-wallet alternative will probably be a better fit. Those options may also be more familiar at checkout and easier to replace if one payment method stops working. MyCard needs to be judged as a specialized tool, not as a universal answer to mobile finance.
The price changes the calculation. At $17.99, this is not an impulse download that can be casually forgotten after curiosity fades. I would expect to use it regularly before considering the purchase worthwhile. Someone who taps to pay several times a week may eventually feel that the convenience justifies the cost. Someone who usually carries a card and rarely pays by phone may find that the novelty ends before the app has earned lasting space.
Whether the habit survives beyond the first month
The month-to-month value depends on repetition. A contactless payment app does not necessarily become more useful because it has more content; it becomes more useful when it removes a small amount of friction from a routine you perform again and again. If MyCard works reliably with your phone and usual terminals, its recurring benefit is straightforward: the payment method is always near you, and you can leave the physical card at home more often.
I would measure that value by asking a practical question: after the first few weeks, do I reach for MyCard automatically, or do I still prepare a physical card every time? If the answer is the former, the app has passed the most meaningful test. If the answer is the latter, the $17.99 purchase becomes harder to defend. A payment tool does not need to entertain me, but it does need to become part of muscle memory.
One useful workflow is to assign the app a clear role instead of trying to make it handle every payment situation. I might use it for everyday shops and keep a physical card for travel, emergencies, or places where I am unsure about contactless support. This division prevents a single failed tap from disrupting the whole day. It also makes the app easier to evaluate: I can see whether it is genuinely reducing the number of times I carry or use a physical card, rather than expecting it to replace every alternative immediately.
Another non-obvious consideration is the cost of switching habits. A physical card offers a familiar visual and tactile confirmation, while a phone payment can feel less certain until I see the terminal respond. During the early period, I would pay attention to the complete interaction: how quickly the app is ready, whether the phone is easy to position, and whether I feel confident that the transaction has finished. A tool can be technically functional yet still fail to become a habit if the user is repeatedly unsure what happened.
That confidence is particularly important when paying in a hurry. I prefer a method that lets me move on without repeatedly checking whether I tapped correctly. If MyCard gives me that reassurance in my regular locations, the app has a reasonable chance of remaining useful. If each purchase requires extra attention, the convenience advantage over a card becomes much smaller.
How it compares with ordinary alternatives
The obvious alternative is a physical bank card. A card does not depend on phone battery, screen condition, or the user remembering to bring the device. It is also familiar to nearly every cashier and terminal. MyCard’s advantage is convenience when the phone is already in hand, especially for people who want to carry fewer objects. The card’s advantage is resilience and simplicity. Neither wins in every situation.
A broader mobile wallet is another comparison point. Such services may be preferable if you want a widely recognized payment ecosystem, support for several cards, or a more established set of account and security controls. MyCard may appeal more to someone who wants a focused app and does not need a large platform around the payment action. The trade-off is that a narrower tool may offer less flexibility when your financial life becomes more complicated.
I would also compare the purchase with simply using a bank’s own mobile payment option, if one is already available and works well on the phone. The bank’s solution may feel more directly connected to an existing account, while MyCard’s appeal is its dedicated focus on contactless payment. The better choice is the one that works consistently with the card you actually use, not the one with the most attractive promise.
Maintenance is small, but it is not zero
The maintenance burden is easy to underestimate because payment apps are quiet when everything works. You still need to keep the phone in usable condition, maintain enough battery for the moment you need to pay, and pay attention when the operating system or app changes. The current version is 1.21, and although version numbers alone do not tell me how often maintenance occurs, I would treat updates as part of owning a payment tool rather than ignoring them.
I would also avoid making MyCard the only way to access money. A backup card is sensible, and I would keep it separate from the phone so that losing one does not automatically remove every payment option. This is one of the most practical habits for any phone-based payment setup. It does not cancel the convenience; it protects it by preventing one device problem from becoming a financial emergency.
Device changes deserve attention too. If I replace my phone, I would not assume that the payment setup will transfer exactly as before. I would plan time to check the new device, test a small purchase, and confirm that the app is ready before depending on it. The same applies after a major reset or other change that affects the phone’s configuration. A contactless app is part of a hardware-and-software chain, so maintenance includes the phone itself.
Security habits matter without needing to become complicated. I would use the phone’s normal lock protection, avoid lending an unlocked device, and treat the app as a payment instrument rather than a casual utility. I would also review the payment result at the terminal instead of walking away immediately after a failed or ambiguous tap. These steps are common sense, but the convenience of tapping can make people rush through them.
Where fatigue can appear
The first source of fatigue is inconsistency. If the app works beautifully at one terminal but requires repeated attempts at another, I start carrying the physical card again. Contactless payment is appealing because it should feel effortless; every exception has a disproportionate effect on trust. Even a small number of awkward checkouts can make me hesitate before leaving the wallet behind.
The second source is dependence on the phone. A low battery, a bulky case, a damaged screen, or a phone that is difficult to wake can turn a quick payment into a public troubleshooting session. MyCard does not change that basic vulnerability. For some people, this is acceptable because the phone is already part of every outing. For others, the physical card remains the calmer option precisely because it has fewer moving parts.
The third is financial value. Paying $17.99 for a focused utility requires a clearer reason than downloading a free experiment. If I use the app repeatedly and it changes how I carry my essentials, the cost can feel reasonable. If I only use it occasionally, the purchase may feel like paying for an idea rather than a lasting service. I would make that decision based on expected frequency, not on the excitement of the first successful tap.
There can also be fatigue from uncertainty about compatibility. A reader may reasonably ask whether every bank card or every terminal will work exactly the same way. I would not promise that. The responsible approach is to check the intended setup before purchase, test it in familiar places, and keep a backup while learning its boundaries. That answer is less exciting than a blanket guarantee, but it is much more useful for a payment app.
Another practical question is whether the app is suitable for travel or emergencies. I would treat it as a convenient local payment method rather than my sole emergency plan. Travel adds unfamiliar terminals, different payment expectations, and more serious consequences if the phone fails. MyCard may still be helpful on a trip, but I would bring a physical alternative and avoid assuming that a contactless setup tested at home will cover every situation.
My long-term verdict on MyCard
After the novelty fades, MyCard has one clear path to lasting value: it must become a dependable part of a narrow, repeated routine. I like the idea of a dedicated contactless payment app because it avoids pretending to be a complete financial dashboard. For the right user, that focus is refreshing. The app can earn its place when the phone is already the object you carry everywhere and the payment experience is smooth enough to become automatic.
My reservations are equally clear. The upfront price makes casual experimentation expensive, and the app’s usefulness is tied to hardware, phone condition, payment compatibility, and personal habit. It is not the best choice for somebody who wants broad banking features, several financial tools in one place, or the strongest possible fallback network. A physical card or established mobile wallet may be more sensible when reliability across many situations matters more than reducing wallet clutter.
My advice is to decide based on your routine rather than the promise of contactless payment itself. If you regularly pay in person, already keep your phone ready, and are willing to test the setup carefully before relying on it, MyCard could provide a simple and lasting convenience. If you rarely use NFC payments or dislike maintaining a phone-dependent backup plan, the app is unlikely to justify its cost.
The lasting value is not the novelty of tapping a phone; it is whether MyCard quietly removes a repeated inconvenience without creating a new one. I would recommend it selectively, with a backup card and realistic expectations. Road Dogs has made a focused finance app for a specific job, and that job can be useful—but only when the app, the phone, and the user’s everyday payment habits all line up.
MyCard - Contactless Payment FAQ
What is MyCard - Contactless Payment and how does it work?
MyCard - Contactless Payment is designed to let users make payments with a compatible smartphone instead of using a physical card. After adding or linking an eligible payment card, you can usually unlock your phone and hold it near a contactless terminal. The transaction is completed through near-field communication (NFC), provided that your device, card issuer, and merchant terminal support the required payment system.
Is MyCard - Contactless Payment compatible with every Android or iOS device?
No. Compatibility depends on the operating system, device hardware, NFC availability, and the payment service supported in your country. On Android, NFC must generally be built into the phone and enabled in settings. iPhone support may depend on the app’s official availability and regional restrictions. Before downloading, check the store listing and confirm that your card issuer and smartphone model are supported.
Is it safe to use MyCard for contactless payments?
Contactless payments are generally protected by several security measures, such as device authentication, tokenized card details, and encrypted communication. Merchants typically do not receive your full physical card number during a transaction. However, you should still use a screen lock, keep the application updated, avoid sharing verification codes, and immediately contact your bank if your phone or payment card is lost or suspicious activity appears.
Can I use MyCard - Contactless Payment without an internet connection?
In many contactless payment systems, a temporary internet connection may not be required at the exact moment you tap to pay, because the phone can use securely stored payment credentials. Nevertheless, the app may need internet access for setup, card verification, account synchronization, security checks, or updates. Availability can also vary by issuer and payment network, so it is wise to keep mobile data or Wi-Fi available when configuring the service.
Are there fees, spending limits, or restrictions when paying with MyCard?
The application itself may not charge a separate fee for every contactless transaction, but your bank, card provider, mobile operator, or payment network could apply its own charges. Contactless payments can also be subject to card limits, merchant limits, offline transaction rules, and regional restrictions. Review the app’s terms and your card agreement carefully, particularly if you plan to use MyCard abroad or for larger purchases.











